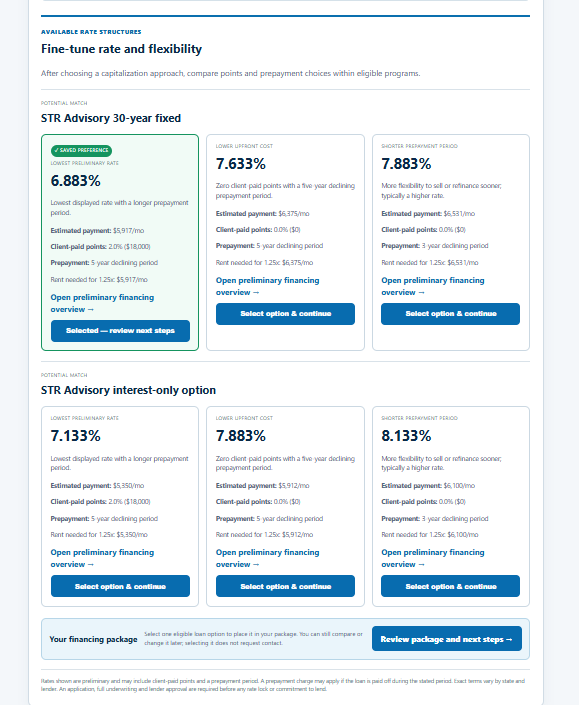
A loan structure includes more than its rate. Compare the upfront costs and exit terms with the period you expect to hold the loan.
Understand points #
One point equals 1% of the loan amount. On a $400,000 loan, one point is $4,000. A zero-point option does not mean there are no lender fees, third-party costs, or prepaid items.
Check the payment tradeoff #
For a simple comparison, divide incremental upfront cost by monthly payment savings. An additional $4,000 cost for a $100 monthly reduction has a simple 40-month payback. This excludes time value, taxes, and other differences and is not a recommendation.
Review early payoff terms #
Read the actual prepayment structure, duration, and triggers. A planned sale or refinance can change the value of a lower-rate option. Do not assume every property or borrower has access to a no-prepayment-penalty option.
Use the date and assumptions #
Displayed financing options are preliminary and can change. Confirm current terms through review; saving an option does not lock a rate.
Related help #
Analyze a Property · Contact STR Advisory
Property and financing outputs are preliminary estimates, not an approval, rate lock, commitment, or guarantee. Eligibility and final terms require professional review and lender underwriting.


