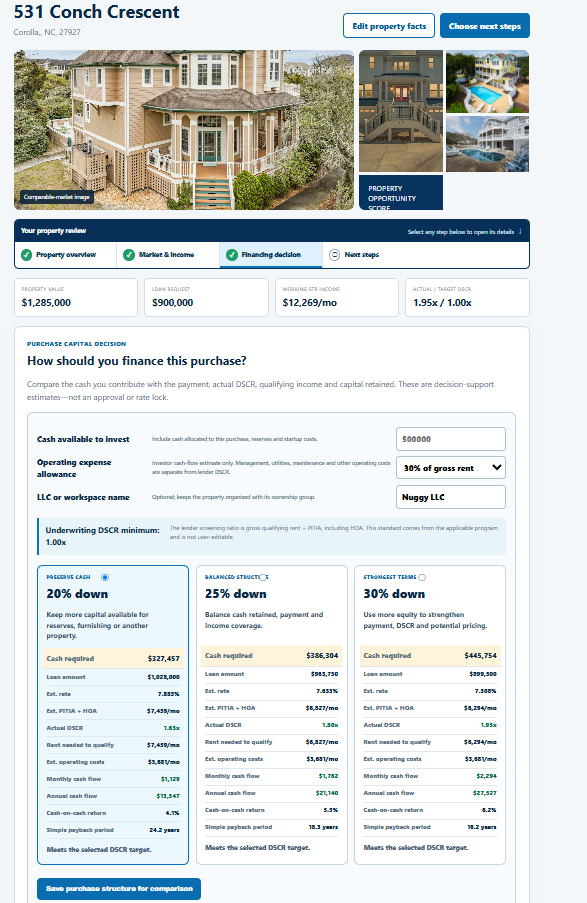
Compare the cash you preserve with the payment you save. A lower loan balance may improve payment economics while using more of your capital.
Calculate the loan amount #
For an illustrative $500,000 purchase, 20%, 25%, and 30% down equal $100,000, $125,000, and $150,000. The corresponding loan amounts are $400,000, $375,000, and $350,000. These are arithmetic examples, not available financing offers.
Read the complete comparison #
Review rate, payment, points, prepayment terms, estimated cash to close, and cash flow together. Different leverage choices may have different preliminary pricing or program eligibility, so holding the rate constant is useful only as a controlled example.
Protect operating liquidity #
Account for closing costs, prepaid items, required reserves, furnishings, repairs, and your own operating cushion. The lowest monthly payment may not be the best fit if it leaves insufficient cash for the transaction and operation.
Related help #
Analyze a Property · Contact STR Advisory
Property and financing outputs are preliminary estimates, not an approval, rate lock, commitment, or guarantee. Eligibility and final terms require professional review and lender underwriting.


