Purchase a furnished rental
Test the proposed rent and vacancy assumptions. Include furnishings, utilities, repairs and reserves alongside closing costs.
Plan your first rental purchaseFurnished Finder rental-property financing
Buying or refinancing a furnished rental? Review lease income, vacancy between stays and expenses, then compare estimated payments and cash required.
Free registration required to view estimated rates and save your research. No sales call required. Contact our team when you choose. Estimates are subject to lender review.
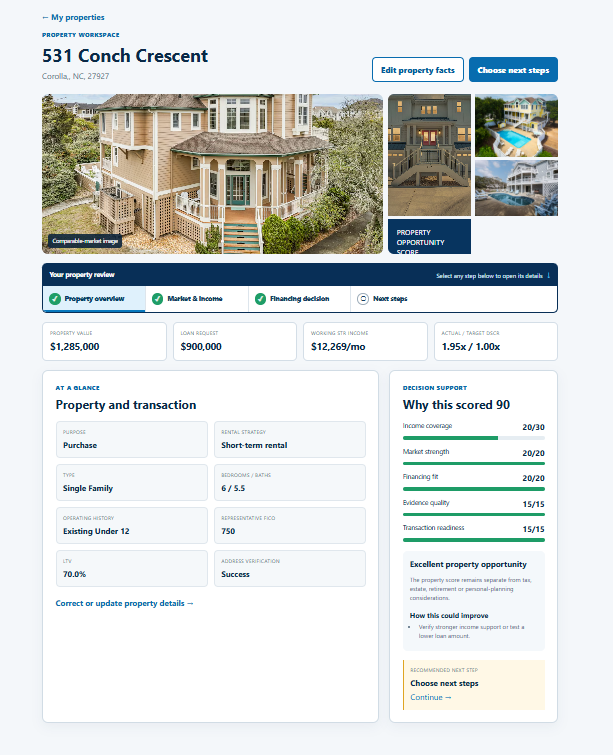
An eligible furnished rental may qualify using lease or market-income evidence accepted by the lender. A Furnished Finder listing, a 30-day stay or a signed lease does not automatically establish qualification. Property use, income evidence, credit, leverage, reserves, ownership and location still matter.
Test the proposed rent and vacancy assumptions. Include furnishings, utilities, repairs and reserves alongside closing costs.
Plan your first rental purchaseCompare the current loan with a potential replacement using documented rental activity and the full cost of refinancing.
Explore financing objectivesEstimate net proceeds, retained equity and the new payment. Consider whether the property can support the additional debt.
Review portfolio decisionsDocument rent, term, start and end dates, included utilities, deposits and any cancellation provisions. The lender determines whether and how the agreement can support qualifying income.
Organize executed agreements, rent collections and management statements. Explain tenant gaps, concessions and differences between scheduled rent and money received.
Label income as projected. Support assumptions with relevant market evidence where available. Asking rents are not proof of collected rent or occupancy.
Reconcile direct agreements and other booking channels by property and period. Avoid counting the same tenancy or payment twice.
Buy well
Proximity to a hospital, employer or university can inform research. It does not guarantee tenant demand, occupancy or income.
The screen shows an STR research workflow. It is not a Furnished Finder data integration or a verified mid-term rental case. Mid-term income evidence needs its own review.
Explore mid-term rental considerations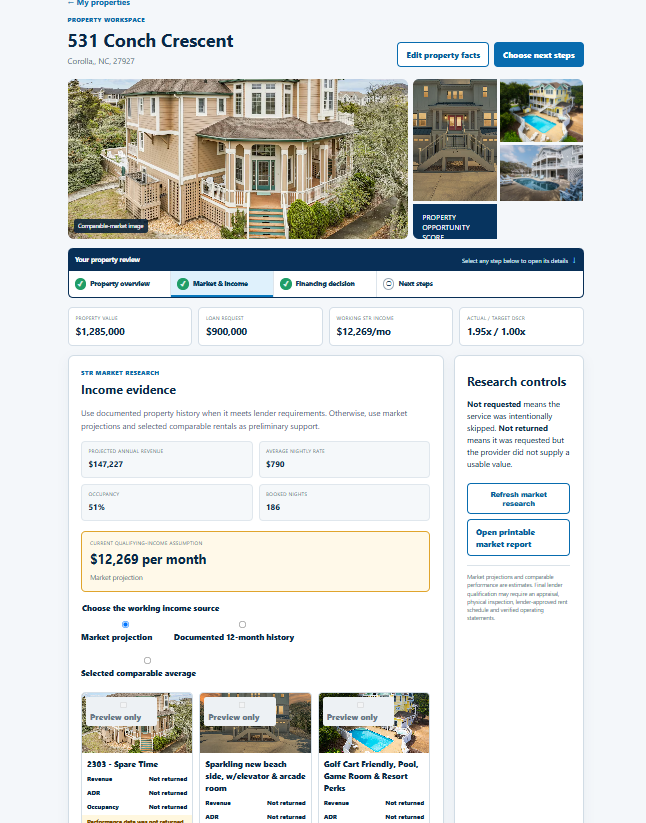
Illustration only
At a hypothetical 1.20 requirement, that payment obligation would need $3,000 in qualifying monthly income. Actual income adjustments, payment definitions and minimum ratios vary by program.
A furnished rental may also pay utilities, internet, cleaning, management, maintenance and furniture replacement. Deduct these costs separately when estimating operating cash flow. DSCR is not a take-home cash calculation.
Understand DSCR and cash flowFinance well
Evaluate down payments, leverage, preliminary rates, payments, points and prepayment terms. Keep enough cash for initial furnishings and tenant gaps.
For a refinance, include closing costs and existing prepayment obligations. For cash out, compare net proceeds with the higher debt payment and retained equity.
Compare loan structures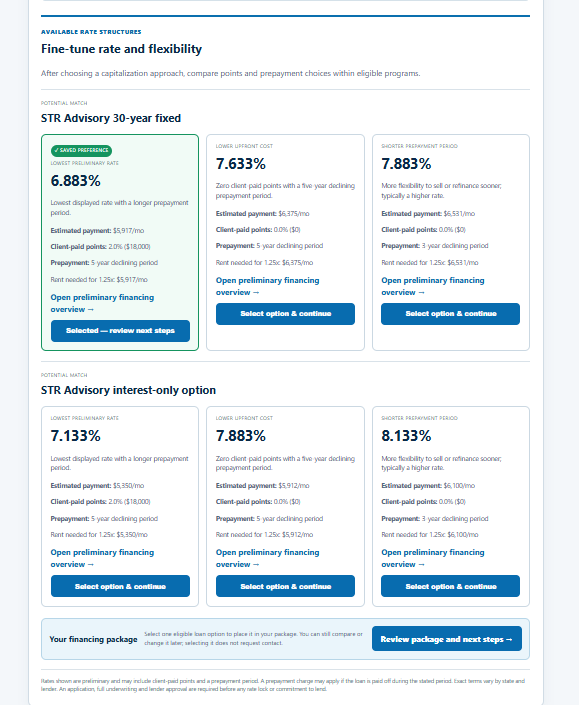
Some eligible programs allow an LLC borrower. Entity documents, authorized signers and personal guarantees depend on the lender and transaction.
Review title, liability, insurance and tax questions with your attorney and CPA before making ownership changes.
Review shared ownershipSave the analysis and a preferred option. Our team can review the package, identify missing information and discuss eligible next steps toward an application.
See how human review worksNo. Lenders determine rental classification, accepted lease terms, income evidence and qualifying adjustments. Local rules and actual property use also matter.
Reflect gaps in the operating history and cash-flow assumptions. Stress-test the cost of vacancy and turnover rather than assuming continuous occupancy.
Some programs may accept approved market-income evidence; others require different support. Preliminary projections do not establish eligibility.
The program defines qualifying income and the payment obligation used in DSCR. Separately account for utilities, furniture replacement and other expenses in your cash-flow analysis.
This page does not promise an account integration. Organize agreements and collection records for review; confirm any available connection in the application.
These may be available through eligible programs. Ownership, guarantees, leverage, seasoning, title and borrower requirements need review.
STR Advisory is independent of Furnished Finder. The name identifies a rental channel and does not imply sponsorship, endorsement or a lending partnership.
Analyze the income assumptions, compare financing and prepare the next steps.
Preliminary estimates are not an approval, application, rate lock or commitment to lend. Financing is subject to underwriting, property and borrower eligibility, lender requirements and applicable state availability. Business-purpose financing is for eligible investment properties. Income, qualification and terms are not guaranteed.