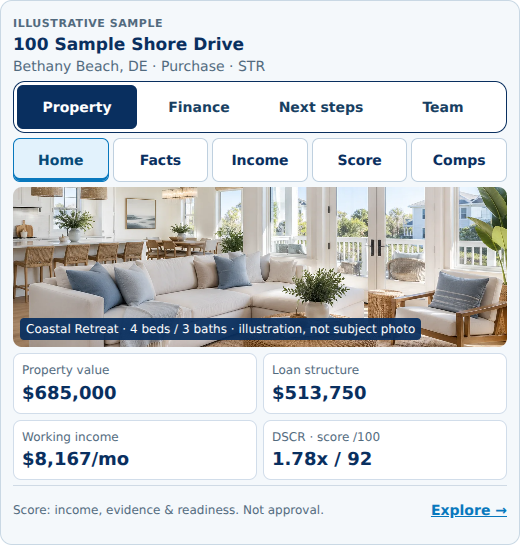
Buy Well
Does the property fit your intended rental model? Examine income evidence, condition, operating costs and permitted use.
Buying your first rental property
Research an Airbnb, Vrbo or traditional rental before you buy. Compare income, expenses, cash needed and estimated financing to see whether the purchase price supports your plan.
Free registration required to view estimated rates and save your research. No sales call required. Contact our team when you choose. Estimates are subject to lender review.
Does the property fit your intended rental model? Examine income evidence, condition, operating costs and permitted use.
What cash does the purchase require? Compare payment, leverage, points, prepayment terms and lender-accepted income.
What still needs verification? Bring your agent and professional advisers into the open questions before the transaction moves forward.
Review nightly demand, seasonality, management, furnishing and turnover costs. Check local and association requirements independently.
Airbnb and STR financingReview local demand for extended stays, included utilities, rental agreements and the gaps between tenants.
Mid-term rental financingReview leases or comparable rent, property condition, collection risk, vacancy and ongoing maintenance.
Long-term rental financingIf personal use is part of your plan, discuss it during financing review. The loan category and representations must match the intended use.
Down payment is only one part of the purchase. Include closing costs, inspections, initial repairs, furnishings where applicable, deposits and operating reserves.
Keep a separate view of cash left after closing. Income can take time to stabilize, and unexpected work can arrive before your first rental payment.
Total planned cash: $175,000.
Illustration only—not a quote or lender requirement. Actual costs and required reserves vary. Avoid counting the same expense in multiple categories.
Income is an assumption to test
Review market evidence and comparable rentals where available. Ask whether the comparisons match the property’s location, condition, amenities and rental model.
Include management, utilities, maintenance, insurance, association dues and other operating costs. Test lower income and higher expenses.
Income used by a lender may differ from your research estimate. A good-looking projection does not establish loan approval or profitable operations.
DSCR compares qualifying income with the payment obligation defined by the lender. Operating cash flow includes your broader expense plan.
If a lender accepts $4,000 of monthly income and uses a $3,000 payment obligation, illustrative DSCR is 1.33. That does not mean $1,000 is available to spend: your operating costs may include additional items.
Hypothetical calculation. Accepted income, payment components and minimum coverage vary by program.
Understand rental-property financingMore down can reduce debt and payment under comparable assumptions, while leaving less cash available for the property. Compare the tradeoff before selecting a preference.
Review rate, points, other closing costs and prepayment terms together. Saving a preliminary option does not lock a rate or approve a loan.
Compare loan structuresVerify property facts, contract timing, inspections and offer requirements. Do not assume a preliminary estimate is a financing letter.
Your attorney can review ownership and contracts. Your CPA can review tax treatment. Your financial adviser can discuss liquidity and portfolio fit.
We organize the property and financing scenario, review possible lender fit and coordinate the financing transaction when you proceed.
Use the platform’s reviewer invitation workflow to share the property discussion. If buying with an LLC member or partner, resolve capital, authority and member obligations with your advisers.
Buying with partnersEnter and verify the address, review assumptions and save the property to your workspace.
Review financing choices, compare other saved opportunities and identify the facts still needing verification.
Ask our team to review the package. Proceed through the secure application and document process when ready; the lender makes the credit decision.
No. You can research an opportunity before making an offer. Use preliminary estimates to identify questions, then verify property and financing facts before relying on them.
Potentially. Investor experience, credit, reserves, leverage, property and other requirements vary by lender. A first purchase is not automatically eligible or ineligible.
Ownership requirements vary. Review legal and tax decisions with your attorney and CPA, and confirm the proposed lender’s requirements.
No. It summarizes decision-support factors and does not replace due diligence, professional advice or lender underwriting.
No credit pull is part of the preliminary property check. Formal financing may require credit authorization and additional documentation.
Analyze the property. Compare the financing. Prepare the transaction.
Outputs are preliminary estimates, not applications, approvals, rate locks, financing letters or commitments. STR Advisory arranges eligible business-purpose financing through third-party lenders and does not fund loans, make credit decisions or guarantee income. Financing depends on verification, documentation, underwriting, borrower and property eligibility, applicable licensing and state requirements.

